Savills

Publication

Market in Minutes - LI&L Q4 2026


The Danish Light Industrial and Logistics (LI&L) market is characterised by moderate vacancy, resilient rent levels and stable investor activity. The Capital Region and the Central Denmark Region account for the majority of transaction activity. International investors continue to show interest in LI&L assets in the Capital Region, however opportunities remain constrained by a limited supply and competition from other European LI&L markets. The development pipeline amounts to approx. 600,000 sqm, annually towards 2028, of which around two-thirds is expected delivered as owner-occupied premises.


STRONG INTERNATIONAL DEMAND DESPITE LIMITED DEAL FLOW

The LI&L transaction volume in 2026 year-to-date remains below the levels recorded in both 2024 and 2025. In 2026 domestic investors have accounted for approx. 81% of the total transaction volume within the sector, with the remainder of transactions completed by international investors. International investors continue to demonstrate significant appetite for acquisitions in the Capital Region, although the availability of suitable investment opportunities remains limited. The LI&L sector’s share of total transaction volume peaked in 2024 when it represented almost 25% of the total transaction volume. In 2026, this share has declined to below 10%.


DEVELOPMENT PIPELINE DOMINATED BY OWNER-OCCUPIER PROJECTS

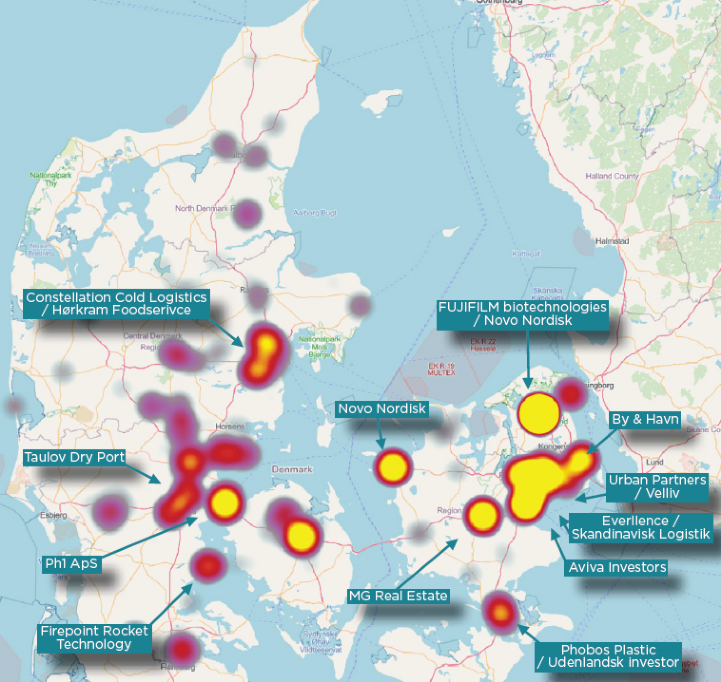
Construction activity within the LI&L sector is stable through to 2028. The most significant development projects are Novo Nordisk, Fujifilm Diosynth Biotechnologies and Everllence, each ranging between 50,000-75,000 sqm.

A substantial proportion of the development pipeline is being delivered for the occupiers’ own use, including projects for Novo Nordisk and Fujifilm, and therefore does not form part of the investable rental market. The remaining schemes are being developed for letting.


LARGE-SCALE PROJECTS DRIVE DEVELOPMENT ACTIVITY

Construction activity within the LI&L sector has remained elevated in recent years, although annual volumes have fluctuated considerably across both time and geography. A key driver of this volatility is the large-scale warehouse and industrial developments commissioned by Novo Nordisk, which account for a significant share of total new-build activity. Development volumes peaked during 2023-2025, particularly in the Region of Southern Denmark. The 2026-2028 pipeline indicates a moderation in activity levels, especially in 2027, when development activity in the Capital Region is expected to decline.

Image treatment